SaaS Forecast Assumption Audit for Revenue Leaders
Audit a SaaS forecast by inventorying material assumptions, assigning owners and evidence, testing sensitivity, and recording decisions on a regular review cadence. The useful output is not a more precise point estimate — it is a visible record of which assumptions can change the operating decision.
This article walks through a four-step review: define the decision and review window, build the assumption register, stress-test the material assumptions, and close the review loop. It is written for Series A and later B2B SaaS leaders who own a revenue forecast and need a repeatable way to challenge it. It does not promise forecast accuracy or any business outcome, and it does not attempt to cover a full go-to-market operating model.
Define the decision and review window
Before opening the model, name the operating decision the forecast is meant to support: a hiring plan, a spend commitment, a runway calculation, or a board plan. That decision is the pass/fail standard for the audit. An assumption matters only if a plausible change in it would change the decision. Without that anchor, an assumption review degenerates into checking arithmetic — confirming that formulas calculate correctly rather than asking whether the inputs deserve the confidence the plan places in them.
Set the review horizon and revision cadence up front. A forecast built to support a twelve-month hiring plan needs a different review rhythm than one built to support a quarterly board update. Forecasting is not a one-off event. As ICAEW’s guidance for auditors puts it, “Management’s production of a forecast is not a one-off event. It will be revisited and revised on a regular basis as new information becomes available and the results of previous decisions feed into actual performance.” Your internal review should work the same way: a standing cadence, not an annual scramble.
The horizon question also determines which assumptions are in scope. A near-term forecast leans on pipeline conversion and collection timing; a longer horizon leans on churn, expansion, and market conditions. Naming the window keeps the audit focused on the assumptions that actually drive the decision at hand.
Be explicit about scope with your team and your board: this audit improves decision visibility. It does not guarantee forecast accuracy, growth, revenue, or any other outcome. What it produces is a documented basis for each material number, so that when conditions change, everyone can see which assumption moved and what decision it touches.
Build the assumption register
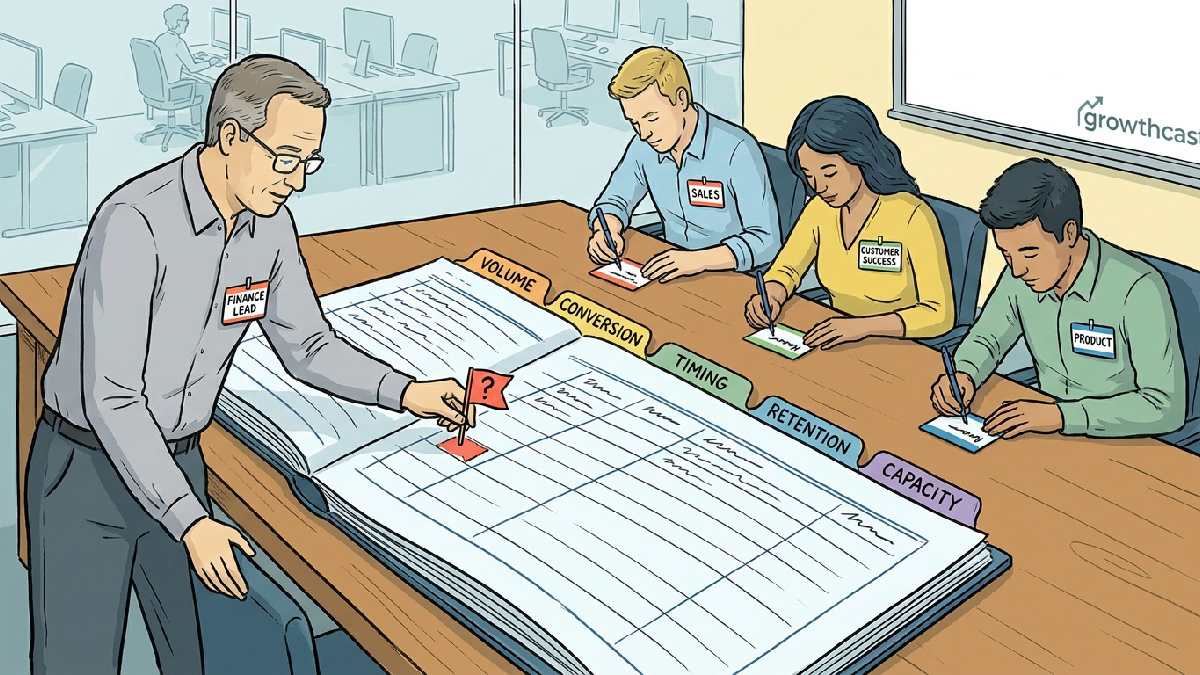
The core artifact of the audit is an assumption register: every material assumption, its owner, its evidence, and when it was last updated. The register is the difference between a forecast that lives in one person’s spreadsheet and a forecast the leadership team can actually govern.
Inventory assumptions across five categories: volume (pipeline created, deals closed), conversion (stage-weighted close rates, sales cycle length), timing (ramp time for new hires, implementation lag, collection timing), retention (gross churn, contraction, expansion), and capacity (whether hiring and onboarding plans can support the volume assumptions). For each entry, record where the number came from, when it was last updated, and who owns it.
Assign an owner to every row. Ownership should follow function where possible: sales owns close rates and pipeline coverage, customer success owns churn and expansion, product owns usage curves, finance owns the aggregation and the reconciliation back to actuals. If a row cannot be assigned to a named owner, that is itself a finding — flag it as an unverified assumption and track it explicitly rather than letting it sit unexamined inside the model.
Require each assumption to rest on historical data or explicit, defensible logic. Churn assumptions should be grounded in cohort data; expansion assumptions in product usage and historical upsell rates; new bookings assumptions in the current pipeline with stage-weighted conversion. Where no data exists yet, say so and label the entry as a forecast rather than a fact. Professional examination standards take the same posture: SSAE 3400 requires the examiner to evaluate whether “Management’s best-estimate assumptions on which the prospective financial information is based are not unreasonable” and whether “all material assumptions are adequately disclosed, including a clear indication as to whether they are best-estimate assumptions or hypothetical assumptions.” An internal register that separates best-estimate assumptions from hypothetical ones is borrowing a discipline that assurance standards already formalized.
Scan for common blind spots while building the register: acquisition cost by channel that has not been updated recently, ramp time untied to actual hiring month, expansion modeled flat across segments that behave differently, burn smoothed across functions, and cash flow that ignores real collection timing. Each of these is an assumption that looks reasonable in aggregate and breaks under scrutiny.
Stress-test material assumptions
Not every assumption deserves equal attention. Concentrate effort on the assumptions that are material to the forecasted amounts, especially sensitive to variation, deviate from historical trends, or especially uncertain. A one-line assumption about office software spend rarely changes a hiring decision; a one-point change in gross churn often does.
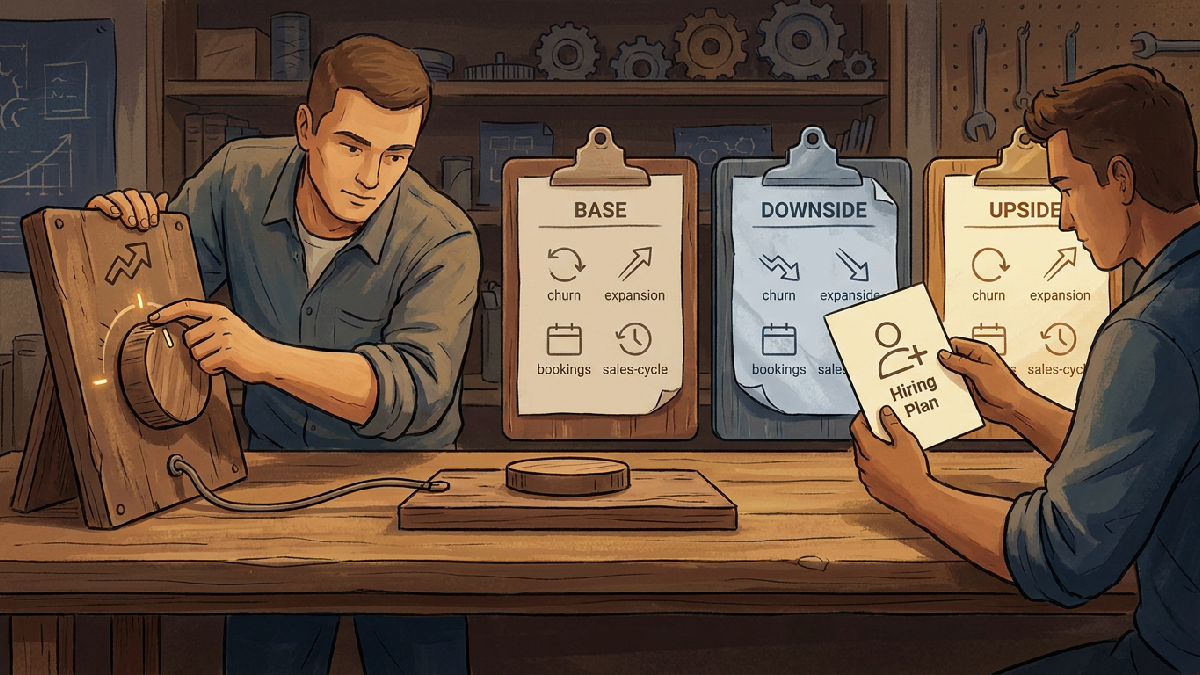
Build base, downside, and upside scenarios with explicit assumption tables — not just three revenue lines. Each scenario should carry its own churn, expansion, new bookings, and sales cycle values, so a reviewer can see exactly which inputs differ between the cases. The question each scenario answers is not “which is right?” but “does the operating decision change across these plausible cases?” If the hiring plan survives the downside case, it is robust. If it only works in the upside case, that is a finding the register should surface.
Run sensitivity checks on the key drivers one at a time: if churn rises by a point, how much ARR is lost at twelve months; if upsells lag a quarter, what happens to cash flow; if the sales cycle stretches, when does pipeline coverage fall below threshold. A sensitivity table showing the impact of a defined change in each key assumption replaces vague risk sections with quantified trade-offs, and it tells the team which assumptions deserve monitoring between reviews.
Map interdependencies explicitly. Hiring versus ramp time: a plan that assumes immediate productivity from new sellers contradicts its own ramp assumption. Growth versus margin: aggressive expansion targets may carry support and onboarding costs the expense side never modeled. Revenue versus cash collection timing: bookings and cash are not the same quarter. Record these dependencies and any lagging evidence alongside the register so the next reviewer sees the reasoning, not just the number.
Keep expectations calibrated throughout. Evidence supporting forward-looking assumptions is itself generally future-oriented and speculative in nature, as SSAE 3400 notes, and prospective financial information “relates to events and actions that have not yet occurred and may not occur.” PCAOB attestation standards frame an examination the same way: the practitioner evaluates “the support underlying the assumptions” and reports on whether “the assumptions provide a reasonable basis for the responsible party’s forecast” — not on whether the forecasted results will be achieved. The goal of your stress test is a reasonable, supported basis for each assumption, not proof of outcomes.
Close the review loop
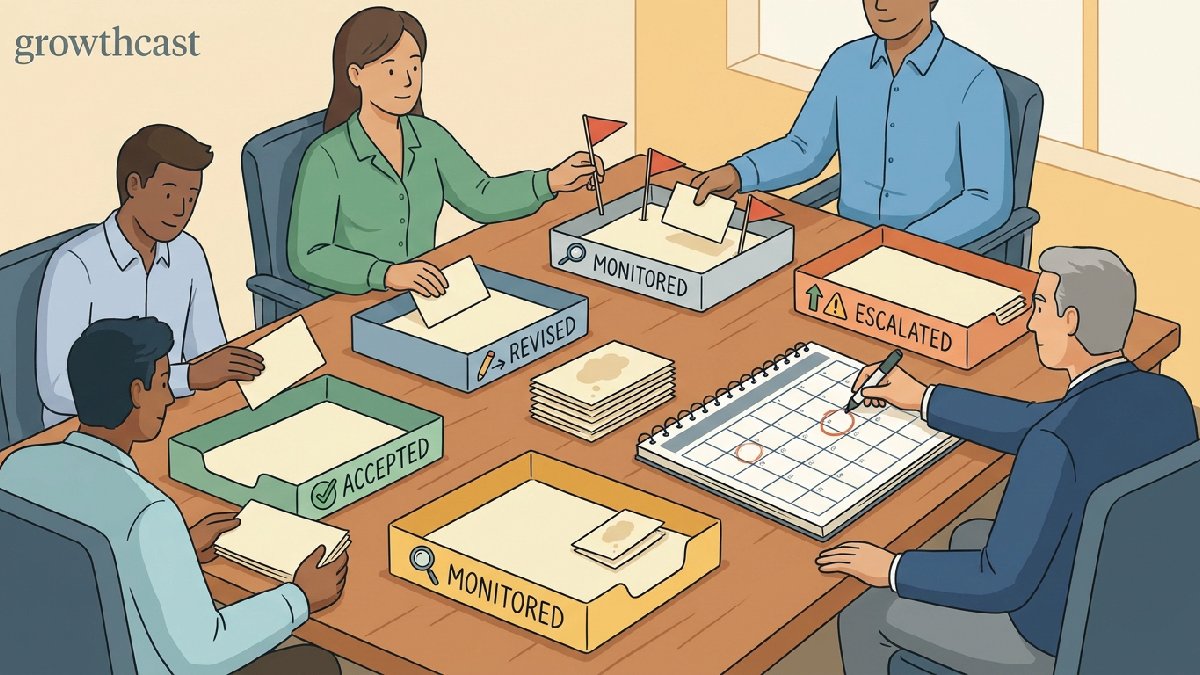
Convert findings into explicit decisions. For each material assumption, record one of four dispositions — accepted, revised, monitored, or escalated — with the rationale and the owner. Accepted means the evidence supports the current value. Revised means the review produced a better-supported value, and the model changes. Monitored means the assumption stands but carries a trigger flag. Escalated means the assumption is material enough and uncertain enough that it needs a decision above the forecast owner.
Set a recurring review: a monthly session comparing forecast versus actuals by component — new, expansion, churned, and contraction revenue separately, not just the aggregate — with sales, customer success, and finance in the room. The component-level comparison matters because aggregate accuracy can hide offsetting errors: expansion overperformance masking a churn problem, for instance, until the cohort matures.
Define trigger flags that force an out-of-cycle review rather than waiting for the calendar: acquisition cost data that has gone stale, pipeline coverage dropping below your defined threshold, a pricing or packaging change not yet reflected in the model, or a hiring plan that slipped a quarter. Each trigger should name the assumption it invalidates and the owner responsible for the revision.
Keep the scope bounded. This audit covers the assumptions behind the forecast; questions about the broader go-to-market operating model belong in a separate discussion — see the GTM operating model for startups. If you want a structured place to run this review, the forecast tool is an optional next step, and readers exploring how the GrowthCast agency works can review how it works — the agency and GrowthCast Forecast are distinct offerings.
Ready to pressure-test your forecast review process? Start a GrowthCast conversation.